

A transaction feels wrong. The source of funds is unclear. The client becomes evasive when questioned. At that moment, the issue is no longer customer service or commercial judgement. It becomes a legal decision.
Under UK Anti-Money Laundering law, once knowledge or suspicion of criminal property arises, regulated professionals are required to act. That action usually takes the form of a Suspicious Activity Report (SAR). SARs are the backbone of the UK’s AML enforcement system. They allow law enforcement to identify patterns, trace criminal networks, and freeze assets before funds disappear.
This article explains how SARs work, when they must be submitted, what happens after filing, and how AML enforcement operates in practice across the UK.
What Is a Suspicious Activity Report (SAR)?
A Suspicious Activity Report is a formal disclosure submitted to the National Crime Agency (NCA) when a person in the regulated sector knows or suspects that money laundering or terrorist financing may be taking place.
The legal basis for SARs comes from the Proceeds of Crime Act 2002 and the Terrorism Act 2000. The obligation applies to individuals working within regulated businesses, not only to the organisation itself.
A SAR is not an accusation. It is a disclosure of suspicion based on available information. The threshold is deliberately low to encourage early reporting.
Suspicious Activity Reports and AML Enforcement in the UK
Suspicious Activity Reports (SARs) play a vital role in the UK's Anti-Money Laundering (AML) framework by helping authorities identify and investigate suspected financial crime. This guide explains when SARs should be submitted, the reporting process, and how AML enforcement measures support compliance, reduce financial risks, and strengthen efforts to prevent money laundering and terrorist financing.
Table of Contents
When Must a SAR Be Submitted?
A SAR must be submitted when:
- A person knows or suspects that criminal property is involved.
- Suspicion arises in the course of business in the regulated sector.
- There is knowledge or suspicion of terrorist financing.
The reporting obligation does not depend on transaction size. There is no financial threshold. Suspicion alone is sufficient.
In most organisations, employees report concerns internally to a nominated officer or MLRO. The MLRO then decides whether an external SAR should be submitted to the NCA.
Delay can create legal exposure. In the regulated sector, failure to disclose suspicion is itself a criminal offence punishable by up to five years’ imprisonment.
The Defence Against Money Laundering (DAML) Process
In some cases, a firm identifies suspicion but is also being asked to carry out a transaction that could amount to a principal money laundering offence under the Proceeds of Crime Act 2002. In these circumstances, simply filing a standard SAR is not enough. The firm may need to request a Defence Against Money Laundering (DAML).
A DAML request is required where the firm intends to proceed with a “prohibited act” — for example, transferring funds, completing a property transaction, or releasing assets — that it suspects may involve criminal property.
The process requires the firm to:
- Submit a SAR clearly requesting a DAML.
- Identify the specific prohibited act it seeks a defence for.
- Wait during the statutory notice period (initially seven working days).
- Refrain from completing the transaction unless consent is granted or the notice period expires without refusal.
If the National Crime Agency refuses consent within the initial notice period, a further moratorium period may apply, during which the transaction must remain on hold while law enforcement investigates.
This mechanism balances two objectives. It allows firms to comply with their legal obligations without automatically blocking legitimate business activity. At the same time, it prevents suspected criminal property from being moved before authorities have the opportunity to intervene.
Firms must handle DAML cases carefully. Prematurely proceeding with a prohibited act before the statutory timelines expire can expose both the organisation and individuals to criminal liability. Clear internal escalation procedures and accurate documentation are essential when invoking this defence.
The Tipping-Off Offence
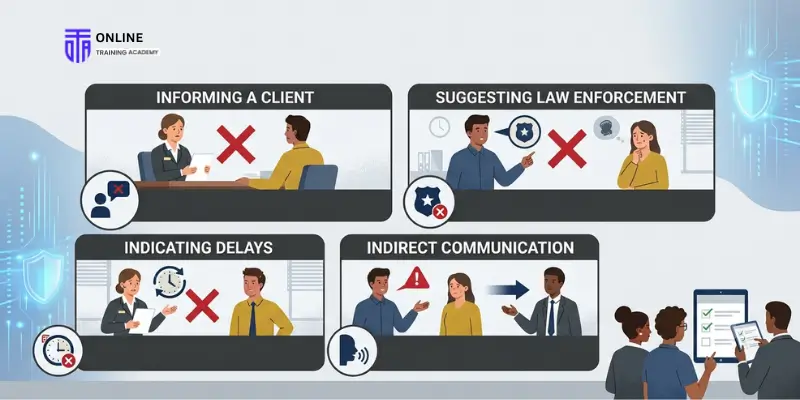
Once a SAR has been submitted, it is a criminal offence to disclose information that could prejudice an investigation. This is known as “tipping-off.”
Tipping-off can occur through:
- Informing a client that a SAR has been filed.
- Suggesting law enforcement involvement.
- Indicating that delays are due to suspicion of wrongdoing.
Even indirect communication that alerts a client may constitute an offence. Staff training must address how to handle transactional delays without revealing protected information.
SAR Volumes and Reporting Trends in the UK
The UK receives hundreds of thousands of Suspicious Activity Reports each year, submitted to the National Crime Agency. While large banking institutions account for a significant share of total reports, thousands of smaller regulated businesses — including solicitors, accountants, estate agents, and money service operators — also contribute.
Several consistent patterns emerge from UK reporting data:
- The financial services sector generates the majority of SARs due to transaction volume and automated monitoring systems.
- A relatively small number of major institutions account for a disproportionately high percentage of total submissions.
- Reporting volumes have steadily increased as supervisory scrutiny and compliance expectations have intensified.
- Non-financial sectors continue to grow in reporting activity as regulatory oversight expands.
It is important to interpret these figures carefully. High SAR volumes do not automatically signal higher levels of crime. Instead, they reflect the wide scope of the UK’s reporting obligations and the low threshold of “knowledge or suspicion.” The system is designed to capture intelligence early, even where criminality is not ultimately proven.
For regulated firms, this trend reinforces a key point: reporting is a routine and expected part of compliance. A low reporting volume does not necessarily demonstrate strong compliance. In some cases, it may prompt supervisory questions about whether suspicious activity is being properly identified and escalated.
What Happens After a SAR Is Filed?
Once a Suspicious Activity Report is submitted, it is received and assessed by the National Crime Agency. The NCA analyses the information alongside other intelligence sources to determine whether further action is required.
Possible outcomes include:
- No immediate action. The report may be retained as intelligence without active investigation.
- Dissemination to relevant agencies. Information may be shared with police forces, HMRC, or other enforcement bodies.
- Initiation of a financial investigation. Authorities may examine linked accounts, transactions, or individuals.
- Asset freezing or restraint. Where appropriate, enforcement powers may be used to prevent movement of suspected criminal property.
In Defence Against Money Laundering (DAML) cases, the NCA has a statutory notice period — typically seven working days — to decide whether to refuse consent to the proposed transaction. If consent is refused, a further moratorium period may apply, during which the transaction must remain on hold while investigation continues.
Firms are not usually informed of the outcome of intelligence assessments. Unless further information is required or enforcement action directly affects the business, the reporting entity may receive no additional feedback. This is normal and does not indicate that the report was unnecessary.
From a compliance perspective, once a SAR is properly submitted and documented, the firm’s immediate legal obligation is generally discharged — subject to any ongoing duties such as maintaining records or complying with DAML restrictions.
Asset Freezing and Recovery Powers
The UK’s AML enforcement regime is not limited to criminal prosecution. It includes extensive asset recovery tools under the Proceeds of Crime Act.
Authorities may:
- Obtain account freezing orders.
- Restrain assets pending investigation.
- Seek confiscation following conviction.
- Pursue civil recovery where criminal conviction is not secured.
The Criminal Finances Act 2017 strengthened these powers by introducing Unexplained Wealth Orders (UWOs). Where assets exceed £50,000 and appear disproportionate to lawful income, courts can require individuals to explain their origin. Failure to provide a credible explanation can lead to civil recovery proceedings.
Professional Reporting Duties and Personal Liability
The duty to report applies to individuals working in the regulated sector. This includes solicitors, accountants, estate agents, and money service operators.
Key points include:
- The reporting duty arises personally, not only corporately.
- Internal reporting mechanisms must be clear and accessible.
- Failure to disclose suspicion can lead to prosecution.
- Legal professional privilege applies only in limited circumstances.
Employees cannot rely on ignorance if reasonable suspicion should have been recognised based on training and role responsibilities.
Enforcement Challenges and Compliance Burden
AML enforcement in the UK involves balancing crime prevention with commercial practicality. Challenges include:
- High reporting volumes that strain investigative capacity.
- Compliance costs for small and medium-sized firms.
- Data protection considerations in record-keeping and monitoring.
- Managing client relationships without risking tipping-off.
Despite these challenges, regulators consistently emphasise that AML compliance is a core governance issue. Boards and senior managers are expected to demonstrate oversight and accountability.
Common Mistakes in SAR Reporting
Firms often encounter similar issues:
- Submitting defensive SARs without clear suspicion.
- Failing to articulate the basis of suspicion.
- Poor documentation of internal decision-making.
- Delaying reporting while seeking additional confirmation.
- Inadequate training on tipping-off risks.
Quality matters as much as quantity. A well-drafted SAR clearly outlines the facts, the observed red flags, and the reasoning behind suspicion.
Conclusion
Suspicious Activity Reports are not administrative paperwork. They are a central pillar of the UK’s AML enforcement system. Every report contributes to a national intelligence framework designed to identify criminal networks and protect the financial system.
For regulated professionals, the decision to report is often uncomfortable. It may disrupt transactions or strain client relationships. Yet failing to report carries far greater risk — legal, regulatory, and personal.
Effective AML enforcement depends on timely, well-reasoned reporting supported by strong internal controls. In the UK framework, vigilance is not optional. It is a statutory duty backed by serious consequences.
FAQs
No. It is a legal obligation when suspicion arises.
Yes, unless law enforcement intervenes or a DAML refusal applies.
Yes. Disclosure that a SAR has been submitted may constitute tipping-off.
It may provide a defence in specific circumstances, but it does not replace proper due diligence.
Learn More
Get a FREE Course
- Learn useful skills online free
- Get CPD accredited certificate
- Add it to your CV today!